Worldwide Import and Export Data Analytics Highlight Emerging Trade Opportunities
2026-11-02
Most traders are still guessing where the next big opportunity will come from. Yet worldwide import and export data already tells a different story — one where overlooked markets are shifting faster than most reports suggest. With Tendata, those shifts become visible in real time, long before they turn into crowded trades. Below, we dig into what the latest numbers reveal — and where the real openings are hiding.
Import Surges That Point to Underserved Markets
A sudden jump in imports for a specific product category often reveals more than just supply chain shifts—it can expose a gap between what local buyers want and what domestic producers are actually delivering. When shipments of niche food items, specialty industrial components, or region-specific consumer goods climb sharply over several quarters, it usually means existing suppliers are either too slow, too expensive, or simply absent from that space. Savvy companies track these patterns not to chase every spike, but to identify where demand is stable enough to justify entering with a tailored offer.
The real insight comes from looking past raw import volumes to the underlying reasons for the surge. Sometimes it's a regulatory change that opened a door, other times it's a demographic shift or a new use case that hasn't been addressed locally. For example, a steady rise in imports of ergonomic tools for aging workers might signal a completely different market than a temporary tariff-driven bump in generic parts. By pairing import data with customer interviews and regional sales trends, businesses can spot underserved niches that competitors overlook because they're too focused on high-volume mainstream categories.
Acting on these signals requires a mindset shift: instead of asking "what can we sell more of?" the better question is "what are people already buying from abroad that we could serve better nearby?" That means shorter lead times, localized support, product adjustments for local standards, or simply a more accessible price point. Import surges are not a guaranteed roadmap, but they are one of the clearest, most honest indicators of unmet demand—because every dollar spent on foreign goods is a vote for something that isn't being offered at home.
Export Niches Quietly Outpacing Expectations
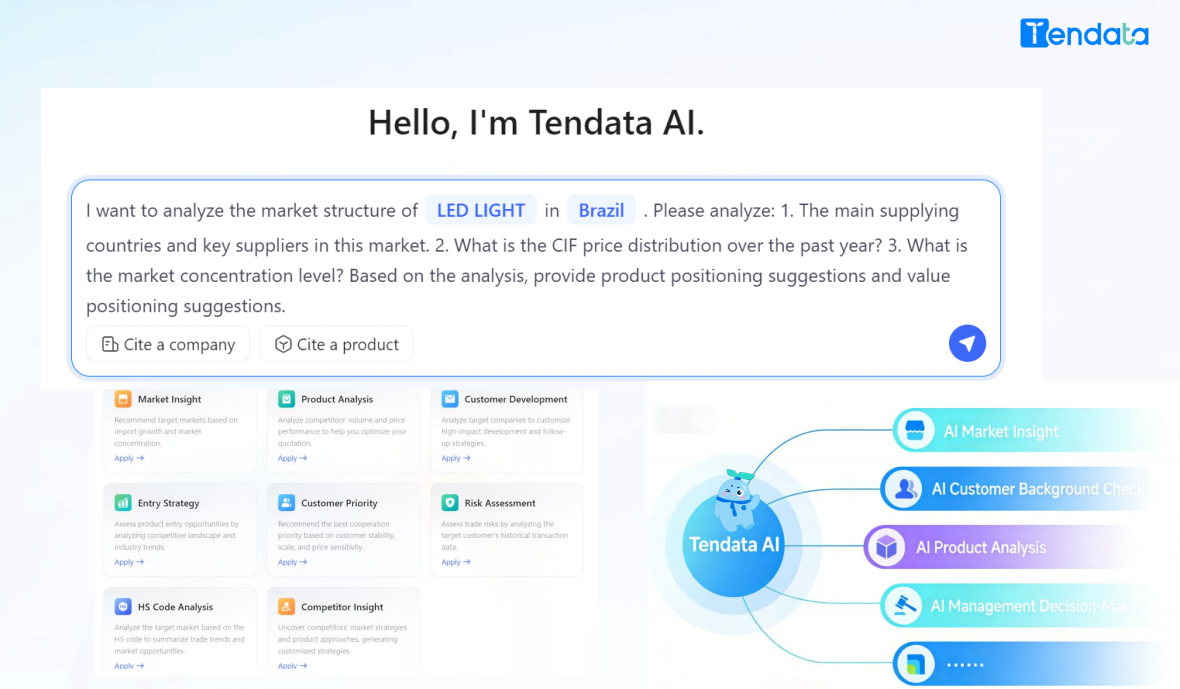
A handful of export categories are moving ahead with little attention, often because their growth hinges on structural shifts rather than temporary spikes. Specialized industrial consumables, certain organic food additives, and precision components for renewable energy systems have all logged sustained double-digit gains in selected trade lanes. Importers in these segments tend to prioritize consistency over price, and once a supplier clears certification hurdles, the relationship becomes remarkably durable.
What stands out is how quietly this momentum builds. Customs brokers and freight forwarders point to specific HS code lines—think ceramic bearings, freeze-dried botanicals, or modular electrical connectors—where bookings run weeks ahead of schedule even when broader trade indicators look flat. These niches rarely make headlines, but their order books tell a different story: steady, compounding demand that doesn't rely on seasonal peaks or consumer sentiment swings.
Part of the reason lies in the nature of the buyers. Many are mid-sized manufacturers or specialized distributors who value supply chain predictability above all else. They don't chase the lowest unit cost; they want a partner who can deliver exact specifications without fail. That kind of trust takes years to build and is hard to displace, which is why these understated export winners keep outperforming expectations long after the initial novelty wears off.
Shifting Trade Lanes and What They Reveal
Cargo routes that once seemed fixed on the map are now bending in unexpected ways. A container that used to move from Shanghai straight to Los Angeles might now stop in Mexico, transfer to rail, and enter the U.S. through Texas. These detours are not random; they reflect deeper shifts in labor costs, tariff structures, and the growing preference for nearshoring. Watching where ships actually go, rather than where they used to go, offers a real-time read on how global supply chains are rebalancing.
Port congestion and geopolitical friction have accelerated the search for alternative corridors. The Suez and Panama canals, long treated as permanent shortcuts, are now viewed with caution. Meanwhile, smaller ports from Vietnam to Morocco are investing heavily in container capacity, hoping to capture traffic that no longer wants to depend on a single chokepoint. This fragmentation of trade lanes quietly redistributes economic leverage, giving midsize economies a chance to become critical nodes that were previously overlooked.
What the shifting lanes reveal is not just logistical adaptation but a change in strategic thinking. Companies are trading a bit of efficiency for a lot more resilience. The old logic of always picking the fastest and cheapest route is giving way to a more layered calculation that weighs political stability, infrastructure reliability, and the cost of sudden disruption. In that sense, a ship’s new path is a map of where trust has moved.
Markets Defying Global Slowdown Patterns
Conventional wisdom suggests that when global growth cools, emerging and frontier markets are the first to stumble. Yet a handful of stock exchanges are charting a different course, powered by local drivers that have little to do with export cycles or foreign capital flows. From Jakarta to Mumbai, pockets of resilience are emerging in sectors tied to domestic consumption, infrastructure build-out, and digital adoption, allowing these markets to shrug off the gloom that has settled over more trade-dependent economies.
The divergence is not accidental. Several of these markets have spent the past decade reducing their reliance on external debt and building up local savings pools. That shift gives them room to maneuver when global financing tightens, and it shows up in the relative stability of their currencies and bond yields. At the same time, policy makers have leaned into reforms that make it easier for domestic investors to deploy capital, from streamlined listing rules to tax incentives for long-term holdings. The result is a self-reinforcing loop: local capital stays home, liquidity deepens, and headline indexes become less tethered to the whims of foreign funds.
Skeptics point out that no market is an island, and a prolonged global downturn will eventually dent corporate earnings everywhere. But for now, the gap between narrative and reality is widening. Analysts who have long treated these bourses as high-beta proxies for world growth are being forced to revise their models, as sectors like renewable energy, logistics, and consumer finance continue to deliver upside surprises. Whether the resilience lasts through another quarter of weak global data remains an open question—but for the moment, these markets are writing their own script.
Under-the-Radar Commodity Flows to Watch
Beyond the headline-grabbing crude cargoes and LNG tankers, a quieter set of commodity flows is redrawing supply maps. Take lithium-rich spodumene from Zimbabwe: instead of heading to established processing hubs in China, a growing share now lands in South Korea and Japan, where battery makers are locking in direct feedstock deals to bypass crowded Chinese conversion capacity. These shipments rarely appear on exchange inventories, yet they influence spot prices far more than many analysts realize.
Similarly, the movement of food-grade phosphates out of Morocco has shifted. With European fertilizer plants trimming output due to energy costs, a niche flow of purified phosphoric acid now travels from Casablanca to Brazil's interior, where it is blended into specialty crop nutrients. This route barely existed five years ago, but drought-driven demand for high-efficiency fertilizers has turned it into a steady monthly occurrence, one that ports in Santos now schedule around.
Finally, watch the quiet arbitrage in recycled aluminum. Baled used beverage cans from the U.S. West Coast increasingly find their way to Malaysia and Thailand rather than domestic remelters, driven by a mix of carbon border adjustments and local scrap surplus. Each container load is small, but cumulatively the flow has grown enough to nudge Midwest secondary alloy prices, a signal most commodity desks overlook until quarterly trade data lands.
Turning Trade Statistics into Market Moves
Raw trade figures rarely move markets on their own. The real signal hides in the gap between what analysts expected and what the numbers actually reveal. A headline surplus can mask collapsing export volumes, while a widening deficit might reflect booming domestic demand rather than weakness. Successful traders learn to read beyond the surface, tracking revisions, seasonal quirks, and the composition of trade flows across sectors.
The conversion from data point to tradable insight demands context. Compare the latest export growth against a six-month trend, not just the prior month. Watch how currency moves lag trade shifts, and which industries drive surprises. For instance, a surge in capital goods exports often signals future business investment abroad, while a drop in consumer goods imports can foreshadow softer retail spending. These relationships turn dry statistics into leading indicators.
Timing matters as much as interpretation. Markets react within seconds of a release, but the full repricing unfolds over hours as desks reassess supply chains and policy implications. Pair the trade balance with industrial production and shipping data to confirm the narrative. Then position accordingly, using options to hedge against revisions. The edge lies not in knowing the numbers, but in anticipating how others will trade them.
FAQ
Detailed shipment records often show rising demand for niche products months before aggregated reports catch up. For example, a steady climb in imports of cold-chain packaging into a region can signal a shift toward fresh food e-commerce, opening doors for suppliers of related equipment or logistics services.
Look at product-level growth rates rather than total trade value. When a specific commodity's import volume rises by double digits for two or three consecutive quarters while its unit price stays stable, that usually means local production isn't keeping pace and importers are actively sourcing new partners.
They compare the import dependency ratio of the target product across markets. A country with high and growing import volume but few supplying countries offers a clearer entry path than a large market with many entrenched competitors. The analytics help quantify the "white space" before committing resources.
By tracking changes in the country of origin for the same product over two or three years, analysts can see when buyers are switching away from a dominant supplier. A sudden diversification of source countries for a key input often indicates that importers want to reduce risk, which opens opportunities for alternative exporters.
Absolutely, small exporters often get the most actionable insights because they can move faster. A modest furniture maker can spot a growing import category in a nearby region, adjust product specs to match the most common dimensions in those shipments, and reach buyers directly through trade promotion agencies without a huge research budget.
One frequent error is looking only at dollar value while ignoring volume and unit price. A rise in import value can simply reflect currency swings or higher raw material costs, not real demand growth. Another mistake is treating one quarter of data as a trend; at least five or six quarters are needed to separate noise from a genuine shift.
The opportunities are more likely to involve services and digital goods alongside physical products. Data flows, software subscriptions, and technical support bundled with equipment show up in trade statistics in new ways. There is also greater emphasis on sustainability-related goods, such as components for renewable energy systems, where import growth is outpacing general merchandise.
Conclusion
Trade data rarely lies, but it often whispers. Recent import surges across Southeast Asia and parts of Africa are pointing to pockets of demand that many suppliers have yet to notice. These are not the usual electronics or automotive components; instead, they include specialized packaging materials, cold-chain equipment, and even niche agricultural inputs. On the export side, small and mid-sized economies are quietly outperforming in categories like processed seafood, technical textiles, and refurbished machinery—sectors that rarely make headlines but consistently beat quarterly forecasts. Meanwhile, under-the-radar commodity flows such as recycled polymers and specialty starches are moving in volumes that suggest structural shifts rather than short-term blips.
Shifting trade lanes add another layer of insight. Several markets in the Middle East and Latin America are decoupling from global slowdown patterns, posting import growth in capital goods even as major economies stall. These anomalies often reveal new production hubs or consumption centers forming below the surface. What matters now is converting these statistics into concrete moves: adjusting sourcing maps, reallocating sales coverage, or entering logistics partnerships before competitors catch on. The patterns are there for those willing to read beyond aggregate totals.
Contact Us
Contact Person: Grace
Email: [email protected]
Tel/WhatsApp: +86 18721992033
Website: https://www.tendata.com